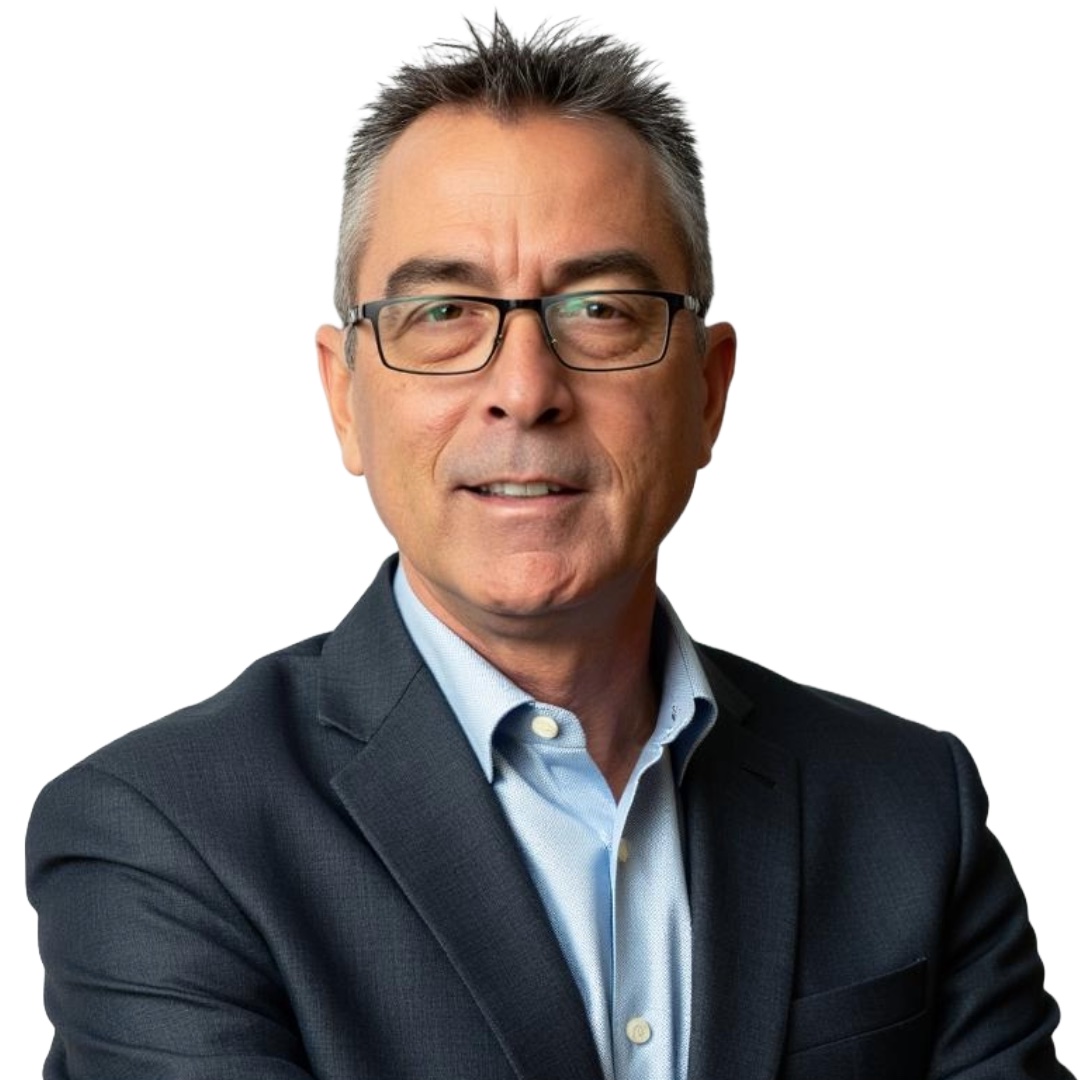
Todd Schofield
Mortgage Broker
FSRA #M08002744
Your lead mortgage broker for financing strategy, lender options and a clear explanation of the choices in front of you.
Meet Todd
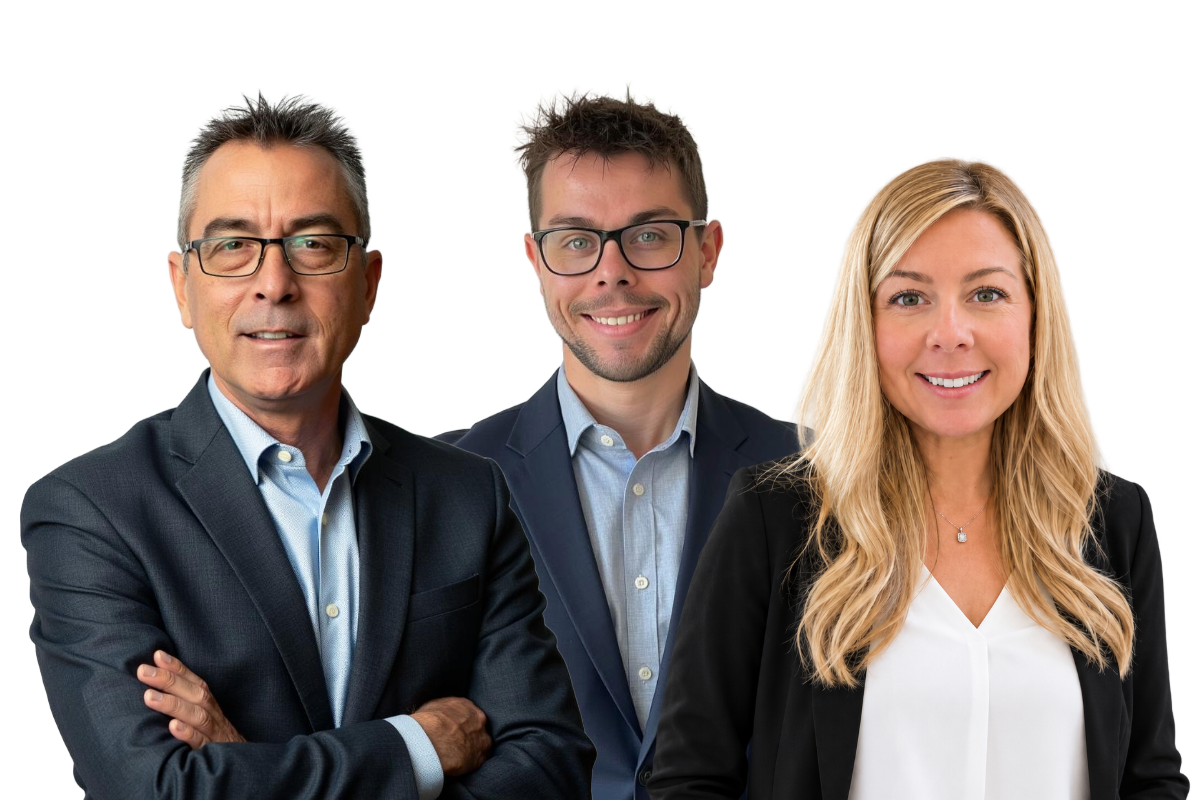
Todd and his team
Mortgage guidance from Todd Schofield, backed by a family team that calls North Bay home. Plan your purchase, renewal or refinance with clear advice and local perspective.
Todd leads your mortgage strategy.Dylan and Ashley help you move forward.
The Mortgage Centre - Todd Schofield, Mortgage Broker (North Bay & Area) - Rock Capital Mortgage, Brokerage
Ontario mortgage services through Rock Capital Mortgage, Brokerage. Brokerage licence #10556.
Mortgage Application
Preparing to buy in North Bay, renew or refinance? Start with Velocity by DLCG, the secure online platform used by Todd and his team. They will review your information and follow up about your goals, documents and available options.
Start your applicationUse the secure application for financial details, rather than ordinary email.
Begin online from North Bay, a nearby community, or wherever your next move starts.
Organize your application so the team can review your situation and explain the next steps.
Todd Schofield · Mortgage advice
Todd helps you prepare for a purchase, compare a renewal or weigh the costs of refinancing. Explore the starting point that fits your situation.
Rock Capital Mortgage, Brokerage · Licence #10556
The Schofield Team · Real estate
Buying or selling in North Bay and area? Todd and Dylan offer separate real estate representation, with local insight into the property side of your move.
Sutton-Choice Real Estate Inc., Brokerage · Real estate services are optional and available separately. You do not need to use them to receive mortgage help.
Todd’s MCC Home Centre App
Use our free Canadian mortgage app to explore a North Bay purchase, renewal or refinance at your own pace. Bring your estimates and questions to Todd for a conversation about the options available to you.
App estimates and pre-qualification are planning tools, not a mortgage approval. A lender must review your application and property.
Available on iPhone & Android


Behind every mortgage
Mortgage Centre Canada is part of DLCG, Canada’s largest mortgage group. That national network sits behind Todd’s local mortgage advice, giving the team more options to investigate for your North Bay plans.
More choice. Room to compare.
Talk with Todd about the terms, costs and flexibility that matter to you.
Comparing options may uncover savings, but a lower rate or payment does not always mean a lower total cost. Savings and approval are not guaranteed.
01
Todd compares available lender options against your budget, timing and plans—not just an advertised rate.
02
Mortgage Centre Canada is a DLCG company, connecting the North Bay team with a mortgage-focused national network.
03
Todd leads the advice, while Dylan and Ashley support application preparation, communication and follow-up.
04
In 2025, 38% of recent Canadian homebuyers obtained their mortgage through a broker—6 percentage points more than in 2024.
05
Broker use among recent first-time buyers reached 48% in 2025, an increase of 10 percentage points year over year.
06
Of mortgage holders who used a broker, 83% would recommend their broker and 72% would use one again. These are national survey findings, not team reviews.
07
DLCG’s national network includes more than 8,800 mortgage agents, supporting the network behind your local conversation.
Sources: Mortgage Professionals Canada, The Broker Advantage (2026); DLCG Q2 2026 results.
70+ lender options
With access to 70+ lender options across major banks, monoline lenders, credit unions and private lenders, Todd can look beyond a single institution. The team compares available terms, explains trade-offs and helps you understand what may fit. Private-mortgage advice is handled by Todd or Dylan.

Access to a lender does not mean every product is available to every borrower. Lender availability, rates, fees and approval requirements vary by application and can change. Financing remains subject to lender review of your circumstances and property.
The people behind your mortgage
Looking for a mortgage broker in North Bay? Todd Schofield helps you understand your financing options, compare the details that matter and prepare a mortgage application that reflects your circumstances. The conversation starts with your goals, budget and timing—not a promise that one lender or product suits everyone.
Mortgage Broker
FSRA #M08002744
Your lead mortgage broker for financing strategy, lender options and a clear explanation of the choices in front of you.
Meet Todd →Mortgage Agent Level 2
FSRA #M22002710
Supporting your mortgage planning, application preparation and questions about financing options alongside Todd.
Meet Dylan →Mortgage Agent Level 1
FSRA #M21004458
Helping keep the mortgage process organized through application support, document coordination and timely follow-up.
Meet Ashley →Local knowledge
Todd, Dylan and Ashley live and work in North Bay, supporting borrowers in Callander, East Ferris, Powassan, West Nipissing, Mattawa and nearby communities. Your property and your plans belong in the mortgage conversation.
A rural or seasonal property may raise questions about year-round access, water and sewage systems, condition or rental use. If you are relocating for work or with the Canadian Armed Forces, bring your dates and income arrangements into the discussion early.
Mortgage support for an Armed Forces relocationExplore vacation and second-home financingFollow along
See the community through Todd and his team’s eyes. Follow Todd, Dylan and Ashley for local moments, home inspiration and mortgage topics to bring to your next conversation.
Follow Todd and his teamBefore you decide
A North Bay mortgage involves more than choosing a rate. Ask Todd about costs, conditions and what still needs to be confirmed.
Explore mortgage calculators →Todd Schofield is the Mortgage Broker leading the mortgage guidance. Dylan Schofield, Mortgage Agent Level 2, and Ashley Schofield, Mortgage Agent Level 1, support clients through planning, application preparation and follow-up. Ontario mortgage services are provided through Rock Capital Mortgage, Brokerage, licence #10556.
Yes. An early conversation can help you understand affordability, down payment, documents and the pre-approval process. A pre-approval is not a guarantee of financing; final approval depends on the lender's review of your circumstances, documents and chosen property.
Review your renewal before its maturity date. Compare your lender's offer with available alternatives, including payment, term, flexibility and any switching costs. A change in income, debts or property use may affect the options you qualify for.
It may be an option, depending on equity, income, credit, property and lender requirements. Compare penalties, fees, the new amortization and total interest cost. A lower payment does not automatically mean a lower overall borrowing cost, and moving unsecured debt into a mortgage puts your home behind that borrowing.
No. Rates, products and approvals depend on the lender, the property and your application. Any rate hold or pre-approval has its own conditions. Todd and the team can explain those conditions and help you understand what still needs to be confirmed.
Costs depend on the lender, mortgage product and transaction. Ask about any broker, lender, appraisal, legal or other fees, especially for alternative or private financing. The team can explain applicable compensation and costs before you decide how to proceed.
The rate matters. So do the terms you will live with after closing. Todd can help you compare an available offer against your plans instead of judging a mortgage on one number.
Payment and total cost. Consider the payment, amortization, applicable fees and interest cost—not just the initial monthly saving.
Fixed or variable. Discuss how each rate structure works and whether changes in rates or payments fit your budget and comfort level.
Prepayment and penalties. Understand extra-payment privileges and how a charge could be calculated if you break the mortgage early.
Flexibility when life changes. Ask about portability, refinancing, restrictions and what a future move might mean under the lender's terms.
The exact requirements depend on your application and lender. Useful starting points include:
Start with your situation. Tell the team what you are trying to do, your approximate timing and the questions you need answered. You do not need to have every document ready to begin a conversation.
Prepare the application. Review income, down payment, debts and property information. The team explains which documents are needed and how to provide sensitive information through the secure application process.
Review the mortgage options. Discuss available lender terms, costs, conditions and the trade-offs relevant to your plans. Ask questions before choosing how to proceed; approval remains subject to the lender's review.
Work through the conditions. The team helps coordinate outstanding requirements and communication as the file moves toward closing. Keep the team informed if your employment, debts, down payment or purchase plans change.
Do not send identity documents, account numbers or financial records through ordinary email. Ask the team how to provide documents securely.
Self-employed mortgages. Business owners and borrowers with variable income often need a more detailed discussion about documentation. Review how your income is earned and reported, your business history, existing obligations and down payment. Different lenders may assess that information differently. Mortgage guidance for business owners
Rental and investment properties. Buying a rental property involves more than the projected rent. Discuss the down payment, existing mortgages, carrying costs and how a lender may recognize rental income. Property use, condition and the number of units can affect the financing options available. Explore investment-property financing
Credit challenges, an unusual income profile or a short-term financing need may call for a closer look at alternative or private mortgage options. Todd Schofield and Dylan Schofield can discuss whether an available option is appropriate, including its costs, risks and intended repayment or exit plan.
Private financing can carry higher rates, additional lender or broker fees and shorter terms. It is not a guaranteed solution or a substitute for checking affordability. Ashley supports the team within her Mortgage Agent Level 1 licence scope; private-mortgage advice is handled by Todd or Dylan.
Todd and his team
“One connected team. A clear starting point for your North Bay mortgage.”
Talk with Todd
Buying in North Bay, approaching renewal or considering a refinance? Tell Todd and the team what you have in mind and when you hope to move forward. You do not need every document ready to begin.
This is an initial inquiry, not a mortgage application. Do not include identity documents, account numbers or financial records here. Use the secure Velocity application when the team asks for financial details.
Checking online request availability. You can still email or call the team below.
For mortgage guidance, real estate help, or both. A brief overview is enough; please leave out sensitive financial or identification details.
This is a request for contact about your needs, not consent to marketing messages.
Ontario mortgage services through Rock Capital Mortgage, Brokerage. Brokerage licence #10556. Each Mortgage Centre is independently owned and operated.
General information, not a mortgage commitment or personalized financial, legal or tax advice. All financing is subject to lender approval and applicable terms.
Real estate is separate and optional: Todd and Dylan also provide local representation through Sutton-Choice Real Estate Inc., Brokerage. You do not need to use their real estate services to receive mortgage help. Learn about separate real estate services.