Licensed people and brokerages
The mortgage and real estate team Todd Schofield, Dylan Schofield, and Ashley Schofield
Mortgage services: Rock Capital Mortgage, Brokerage — FSRA licence #10556
Real estate services: Sutton-Choice Real Estate Inc., Real Estate Brokerage
- Todd Schofield — Mortgage Broker and Real Estate Agent.
- Dylan Schofield — Mortgage Agent Level 2 and Real Estate Agent.
- Ashley Schofield — Mortgage Agent Level 1; Mortgage services only; not a real estate representative..
Armed Forces Relocation
Military Relocation Mortgages and Home Moves in North Bay
Coordinate mortgage, sale, purchase and document questions around a Canadian Armed Forces posting to or from North Bay.
A Canadian Armed Forces posting can make a home move feel less like a single transaction and more like a timed sequence. A current mortgage, a sale, a purchase, temporary housing, remote signing, a relocation administrator and a new community may all need to fit together. The mortgage conversation should identify what is known, what the posting requires and which question belongs to the relocation program, lender, REALTOR®, lawyer or other professional.
The Canadian Armed Forces Relocation Directive (CAFRD) is the official source for applicable relocation benefits and processes. This page is educational mortgage and home-move preparation, not an indication of CAF affiliation, approved-provider status, reimbursement entitlement or guaranteed financing. Eligibility, dates and claim rules must be confirmed through the official relocation channel for the member.
Map the posting before making a home decision
A relocation plan begins with the posting information, reporting date, household needs and current housing position. Before deciding whether to sell, keep, rent or buy, list the deadlines and decisions that can affect one another. A lender can discuss mortgage terms and qualification; a relocation administrator can explain CAFRD; a REALTOR® can discuss property and offers; and a lawyer can address title, contracts and closing.
Sources: Department of National Defence; Financial Consumer Agency of Canada
| Stage | Questions to organize | Responsible source to confirm |
|---|---|---|
| Posting and eligibility | What is the effective date, destination, household status and applicable relocation file? | CAF relocation administrator and current CAFRD |
| Current home | Will it be sold, retained, rented or otherwise handled, and what mortgage terms apply? | Lender, REALTOR®, lawyer and relocation administrator |
| Destination search | What property, commute, occupancy and timing fit the household? | REALTOR®, lender, inspector and local sources |
| Financing | What down payment, closing funds, payout, transfer or qualification is needed? | Mortgage professional and lender |
| Closing and move | How do possession, shipment, temporary housing and reporting dates interact? | Relocation administrator, lawyer, lender and movers |
Sources: Department of National Defence; Department of National Defence; Financial Consumer Agency of Canada
Do not make a financing or sale decision because a relocation benefit is assumed. CAFRD eligibility and mortgage approval are separate decisions, and a reimbursement rule cannot replace a lender’s underwriting or a lawyer’s advice.
Sources: Department of National Defence; Financial Consumer Agency of Canada
Use current CAFRD without assuming an entitlement
The Department of National Defence page currently identifies a CAFRD version dated 1 April 2026 and links previous versions separately. Chapter 8 addresses sale and purchase of a residence, with sections covering commonalities, sale of a principal residence and purchase of a replacement residence. The existence of a section does not mean every member, property, move or cost qualifies; confirm the operative version and the member’s file before relying on it.
Sources: Department of National Defence; Department of National Defence
Verify these before relying on a benefit
- The current CAFRD version and the chapter or section that addresses your move.
- The member’s eligibility, posting status, destination and applicable time limits.
- Whether a cost is reimbursable, paid from a Core or Custom Account, or not covered.
- Whether the residence, transaction, property type or ownership arrangement meets the directive.
- Whether a required approval, contracted relocation service or receipt is needed before spending.
- Whether choosing one benefit affects another benefit or election.
- What must be submitted, by whom, through which official relocation channel and by what date.
Sources: Department of National Defence; Department of National Defence
CAFRD chapter text includes conditions about time limits, arm’s-length transactions, income-producing property, co-ownership, appraisals and the sale or purchase of residences. Only the member’s official relocation administrator can confirm how the current directive applies, what a claim requires or whether a cost is reimbursable. Treat each heading as a prompt to read the operative wording, not as a promise that the team can interpret, endorse or approve a claim.
Sources: Department of National Defence
Independently compiled relocation checklist
Sources: Department of National Defence; Department of National Defence; Financial Consumer Agency of Canada
Gather and record
- Posting message, effective date, reporting date, destination and relocation-file contact.
- Current mortgage statement, maturity date, prepayment privileges, payout process and portability terms.
- Ownership, title, insurance, property-tax, lease and occupancy information for the current home.
- Income, employment, debt, credit, identification and asset records for any new mortgage review.
- Expected sale proceeds or down payment, kept separate from closing, moving and emergency cash.
- Target communities, commute, property type, occupancy and timing at the destination.
- Questions about temporary housing, shipment, travel, remote signing and possession dates.
- A record of official answers, receipts, approvals, deadlines and the person who gave each answer.
- A backup plan if the sale, purchase, mortgage approval, posting date or closing date changes.
- Separate legal, tax, insurance, inspection and relocation questions from mortgage questions.
Sources: Department of National Defence; Financial Consumer Agency of Canada; Financial Consumer Agency of Canada
Use secure document delivery for mortgage records and the official relocation channel for CAF documents. Keep the same names, dates and amounts across the mortgage application, purchase agreement, relocation claim and legal file.
Sources: Financial Consumer Agency of Canada; Department of National Defence
Coordinate the current mortgage and destination home
If the current home will be sold before the term ends, FCAC says breaking a closed mortgage can involve a prepayment penalty, administration, appraisal, reinvestment or discharge fees and possibly repayment of cash back. Ask the lender for a current written payout and ask whether portability or another lender option applies. A relocation directive does not determine the mortgage contract’s payout.
Sources: Financial Consumer Agency of Canada; Financial Consumer Agency of Canada
| Question | Why it matters | Confirm with |
|---|---|---|
| Sell or retain? | A rental or retained property changes mortgage, insurance, tax and relocation questions | Lender, relocation administrator, lawyer, insurer and tax professional |
| Buy before selling? | Timing can create bridge, cash-flow and qualification risk | Lender and lawyer |
| Port or break? | A contract change can create costs or different terms | Current lender |
| Remote coordination? | Identity, signing, inspection and possession must fit the move | Lawyer, lender, REALTOR® and relocation administrator |
| Destination property? | Use, condition, value and access are reviewed for the actual home | Lender, inspector, insurer and local professionals |
Sources: Financial Consumer Agency of Canada; Financial Consumer Agency of Canada; Department of National Defence
A pre-approval does not make the destination property automatically acceptable. FCAC notes that final approval can depend on the property, down payment and updated information. Report changes to employment, debt, funds, occupancy, posting or closing dates before relying on the earlier review.
Sources: Financial Consumer Agency of Canada
Preparing for a North Bay posting
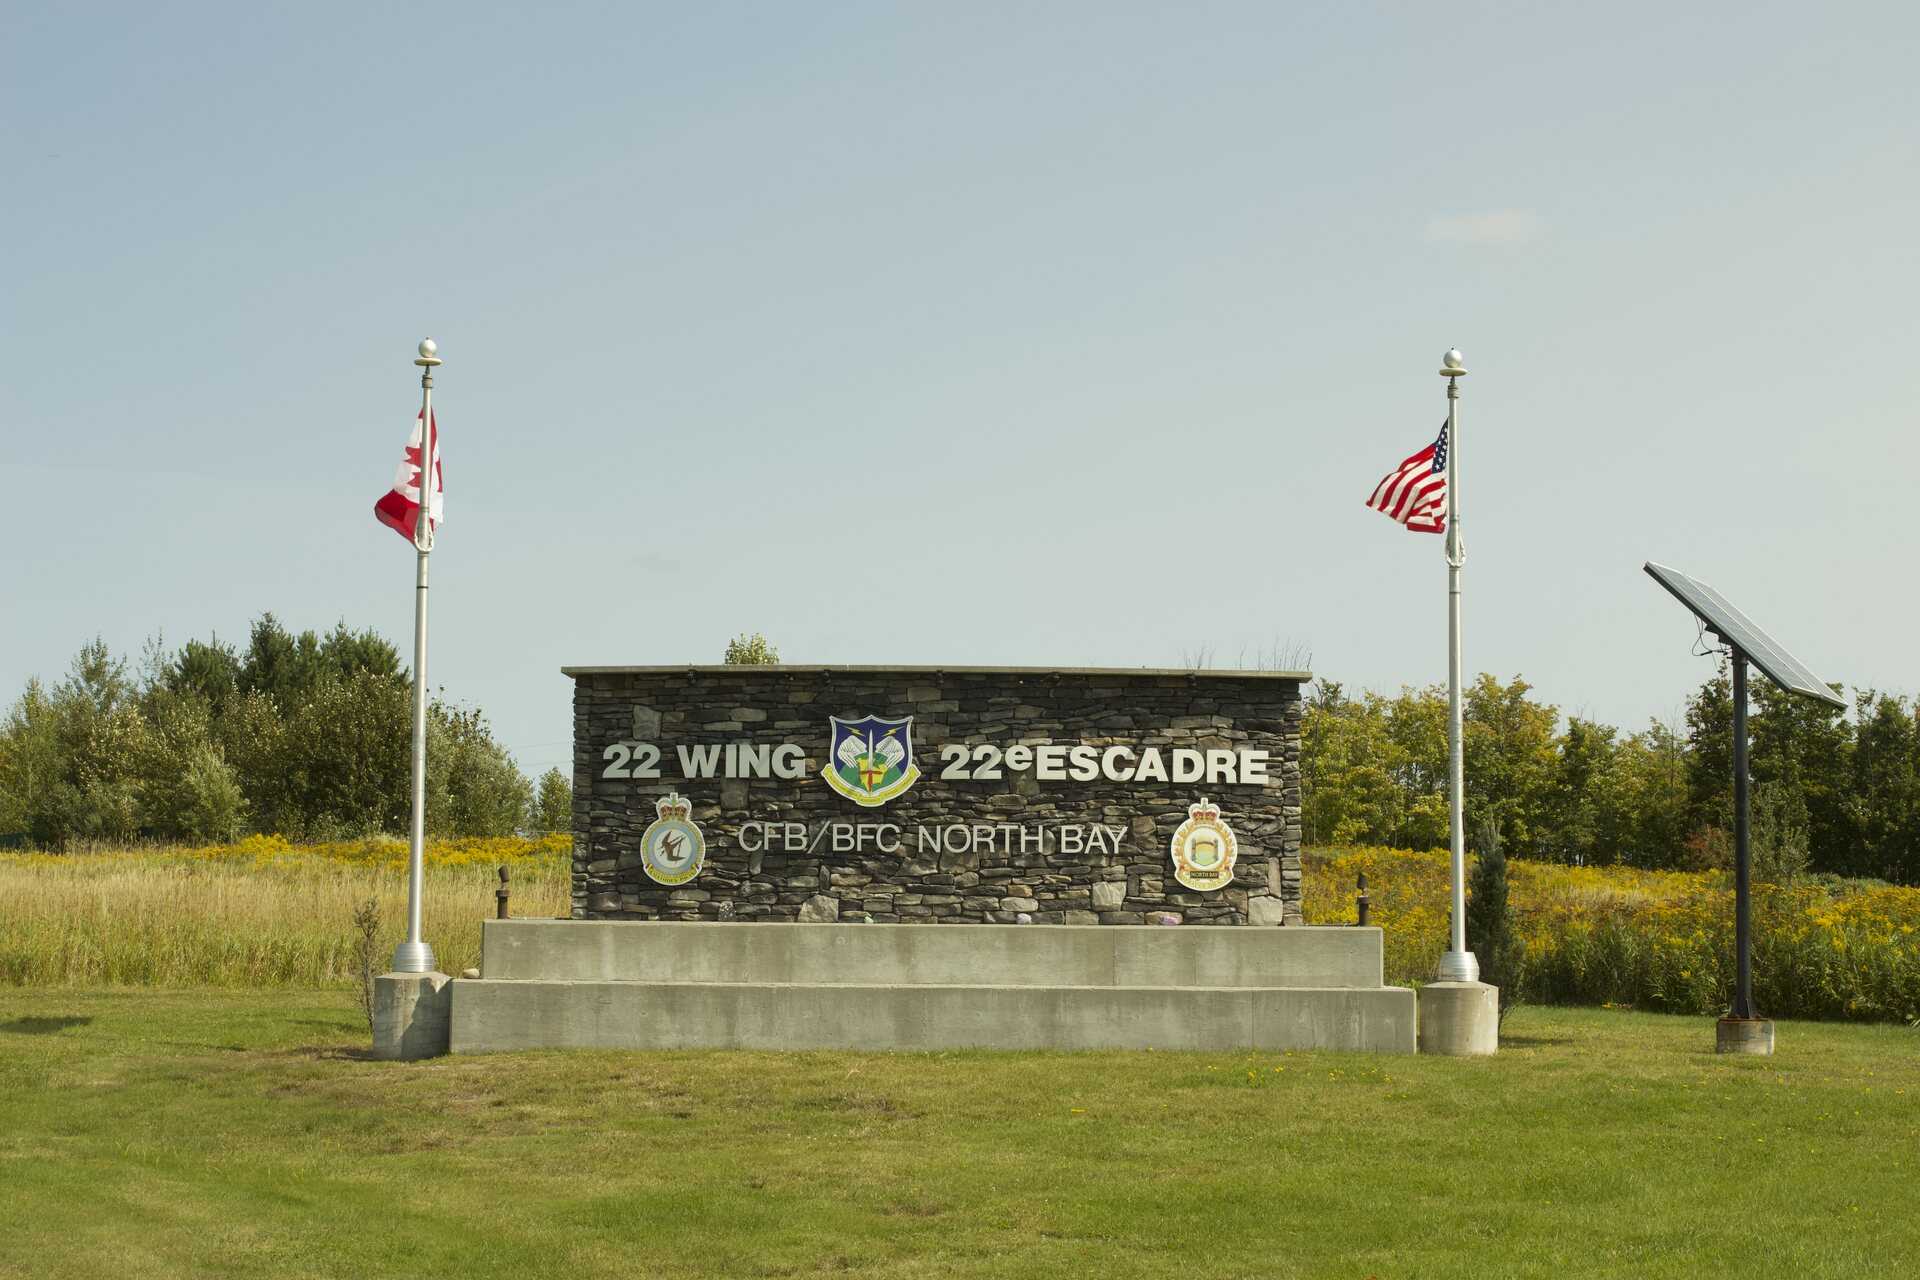
A move to North Bay can involve a new commute, household schedule, school or care planning, winter travel, urban or rural housing and a different set of property questions. The CFB North Bay setting in this page’s image is not an endorsement or claim of military affiliation. For a specific home, investigate access, services, heating, water, septic, insurance, condition and municipal matters through the appropriate sources.
Tell the home and mortgage professionals early
- Whether the move is a new posting, return posting, release, retirement or another housing transition.
- Whether the household needs a primary residence, temporary arrangement, retained property or rental plan.
- Whether the reporting date requires remote viewings, a narrow closing window or temporary housing.
- Whether an existing mortgage, payout, sale, purchase or co-ownership issue is time-sensitive.
- Whether the destination property is urban, rural, seasonal or connected to another residence.
Sources: Department of National Defence; Financial Consumer Agency of Canada
A local mortgage conversation can help organize financing questions; it cannot confirm CAF benefits, military housing, a posting decision or property suitability. Ask for the actual approved roles and document route before sharing personal information.
The sequence may also involve a period when the old home has not sold, the new home is not ready or the member is reporting before the household is settled. Write down the temporary arrangement, expected cash movement and decision deadlines. Ask the relocation administrator about the official treatment of temporary housing and travel, and ask the lender how any bridge, retained-property or occupancy question would be assessed.
Sources: Department of National Defence; Financial Consumer Agency of Canada
When a family is deciding among North Bay neighbourhoods and nearby communities, compare the home itself with the reporting location and daily logistics. A distance estimate, property listing or local suggestion is not a guarantee about winter travel, services, insurance or municipal availability; verify those details before an offer.
Sources: Financial Consumer Agency of Canada
Keep a second copy of the critical dates and contacts somewhere the household can reach during travel or a remote handoff.
Keep the move auditable
Start with the posting information and the current mortgage, then build a dated sequence for sale, purchase, financing, relocation administration, legal work and possession. Keep each answer with its source. If the move changes, update the lender, lawyer, REALTOR® and relocation administrator rather than assuming an old approval or benefit still applies.
Sources: Department of National Defence; Financial Consumer Agency of Canada
Questions people ask before deciding
Does this page confirm that I qualify for CAF relocation benefits?
No. CAFRD eligibility, limits, accounts, receipts, deadlines and approvals depend on the member and posting. DND identifies a current directive version and detailed chapters, but your official relocation channel must confirm what applies to your file.
Can a military posting make my mortgage portable?
A posting does not automatically change the mortgage contract. Ask the current lender whether portability is available, what property and timing conditions apply and how a sale, purchase or increased borrowing would be treated.
What if I need to sell before my mortgage term ends?
FCAC says repaying or breaking a closed mortgage when selling can trigger a prepayment penalty and other fees. Request a current payout, ask about portability and compare the cost with the relocation timeline and any official benefit that may apply.
Can I buy in North Bay before selling my current home?
It may be possible, but the lender will assess income, debt, property, equity, timing and the requested financing. Coordinate the sale, purchase, bridge or other financing questions with the lender and lawyer; do not rely on an estimated sale amount alone.
Sources: Financial Consumer Agency of Canada
What documents should I prepare for a relocation mortgage conversation?
Prepare posting and timing information, identification, income, debts, current mortgage details, assets, down-payment or sale-fund records and property information. The receiving lender or broker decides the complete list and secure delivery method.
Sources: Financial Consumer Agency of Canada
Does the team have an approved CAF relocation-provider status?
This page does not claim an approved-provider status or military affiliation. Ask the official relocation administrator which providers and processes apply, and ask the team to state its actual role before relying on a service or reimbursement assumption.
Sources: Department of National Defence
Can relocation benefits pay my mortgage or closing costs?
Do not assume so. CAFRD contains benefit rules and conditions, while the mortgage contract and closing statement contain separate costs. Confirm each potential expense through the official relocation process, lender and lawyer before committing funds.